The revised ESRS: what the datapoint cuts mean for your FY2027 report
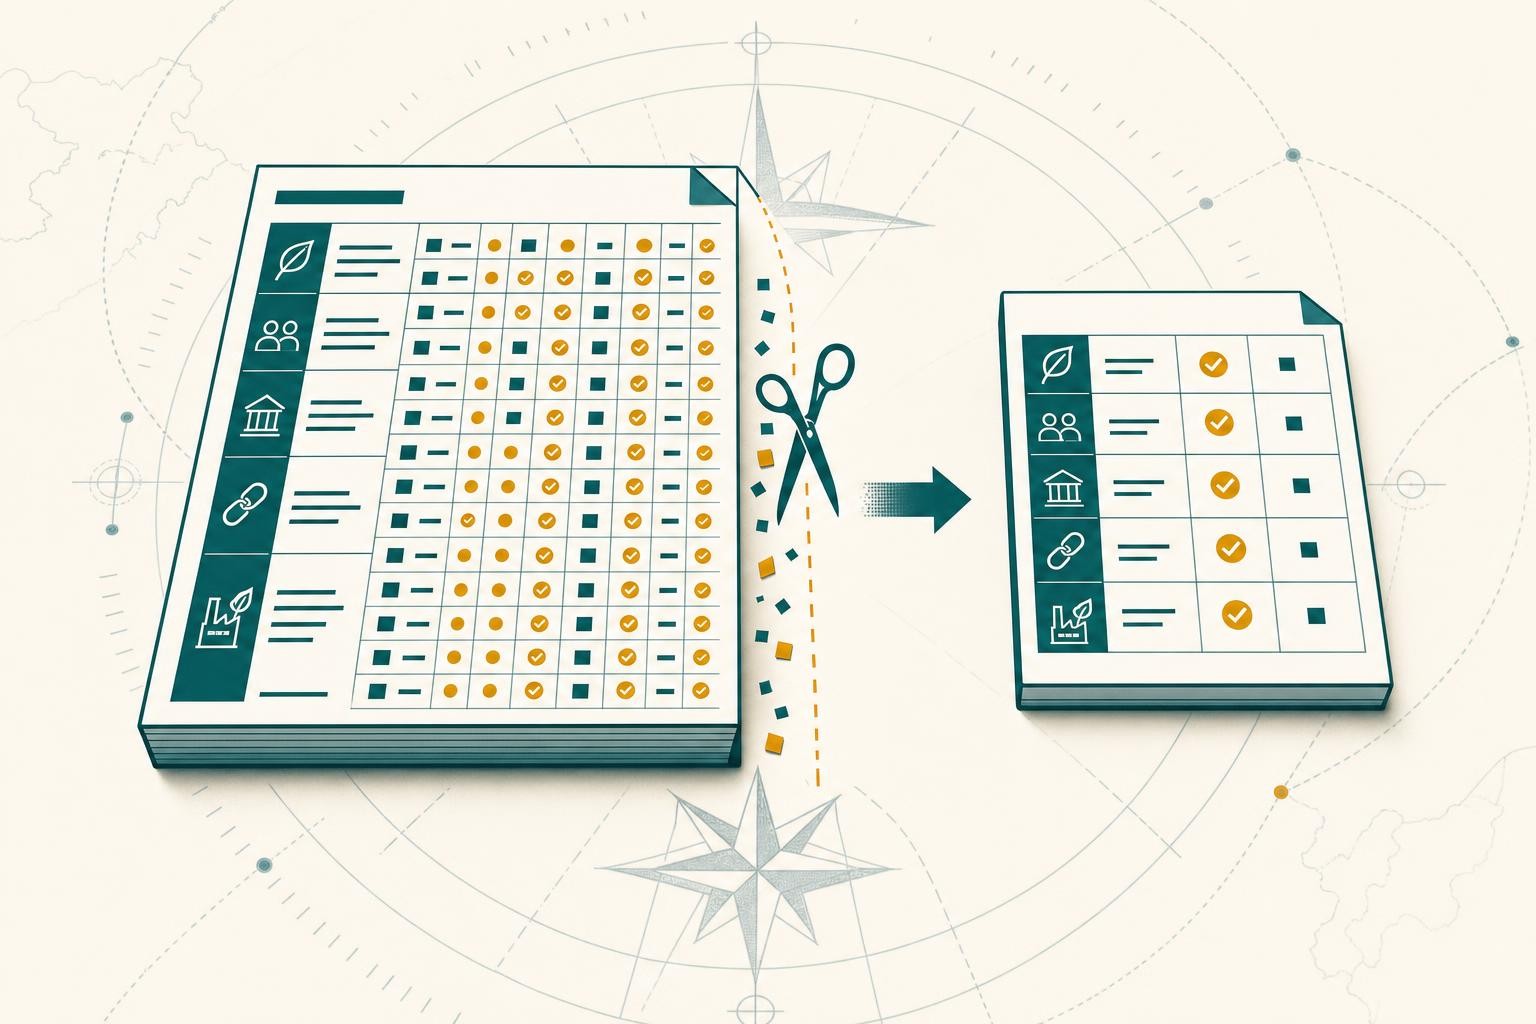
The Omnibus did not just shrink who reports under the CSRD. It also shrank what they report. The European Sustainability Reporting Standards (ESRS) are being revised to cut mandatory datapoints by roughly 60 to 70%, with the new set due to apply from FY2027. Here is what is changing, what is staying, and how to prepare while the final text is still pending.
What the revision does
The ESRS are the rulebook that says exactly what a CSRD reporter discloses. The original first set, adopted as Delegated Regulation (EU) 2023/2772, was widely seen as too heavy. The Omnibus mandated a simplification, and EFRAG, the body that drafts the standards, delivered technical advice on 3 December 2025.
The European Commission then published a draft revised set of ESRS for consultation on 6 May 2026, with the consultation closing on 3 June 2026. The headline aim is to cut the number of mandatory datapoints substantially, by roughly 60 to 70% on the figures cited so far, and to make the standards easier to apply.
Three things you can rely on now
While the detail is still being finalised, three points are stable enough to plan around:
- Fewer mandatory datapoints. The revised standards remove or make voluntary a large share of the data requirements, and lean more on a clear materiality filter so you only report what is material.
- Sector-specific ESRS are dropped. The separate sector standards that were once planned have been removed from the mandate. You will not need to wait for, or comply with, a sector-specific set.
- A lighter materiality approach. EFRAG's guidance encourages a top-down double materiality assessment: conclude materiality at the topic level first, and only drill into detailed impacts, risks and opportunities for the topics that pass. That alone removes a lot of busywork.
What stays the same
Simplification is not the same as repeal. The architecture is intact:
- Twelve standards. Still ESRS 1 and ESRS 2 (cross-cutting) plus E1 to E5 (environment), S1 to S4 (social) and G1 (governance). ESRS 2 general disclosures remain mandatory for every reporter, regardless of materiality.
- Double materiality. The impact-plus-financial test survives as the core principle.
- ESRS E1 (climate) is still the centre of gravity. For almost every reporter, climate is material, so ESRS E1, with its GHG Protocol Scope 1, 2 and 3 emissions, remains the standard you will spend the most time on.
- Limited assurance and digital tagging. Still required.
The timeline
| Milestone | Date |
|---|---|
| EFRAG technical advice delivered | 3 December 2025 |
| Draft revised ESRS published for consultation | 6 May 2026 |
| Consultation closed | 3 June 2026 |
| Target adoption of the delegated act | around 17 September 2026 |
| Revised ESRS apply | FY2027 (early voluntary adoption for FY2026) |
Until the delegated act is formally adopted, treat the exact datapoint counts and wording as not yet final. We track the status on our Omnibus page and update it as it moves.
How to prepare without over-building
The temptation is to wait for the final text. A better approach:
- Do not collect everything. Run your double materiality assessment first and let it scope your disclosures. Our free materiality matrix builder helps you structure it.
- Lock down ESRS E1 early. Whatever the final datapoint count, you will need a credible greenhouse-gas inventory. Start with Scope 1, 2 and 3 and our emissions calculator.
- Track the gaps, not the noise. Build for the disclosures that are clearly staying, and flag the ones that depend on the final text so you can add them quickly once it lands.
FAQ
When do the revised ESRS apply? From FY2027, with early voluntary adoption allowed for FY2026. Adoption of the delegated act is targeted for around September 2026.
By how much are datapoints being cut? Roughly 60 to 70% of mandatory datapoints, on the figures cited so far. The exact number depends on the final adopted text.
Do I still need ESRS 2? Yes. ESRS 2 general disclosures remain mandatory for every reporter, regardless of the materiality outcome.
This is guidance to help you understand the ESRS, not legal advice. The revision is not yet finalised; confirm against the primary sources linked above or a qualified adviser before relying on specific datapoint counts.
Want the final ESRS the moment it is adopted? Subscribe to The CSRD Brief and we will tell you what changed and what it means.
Related reading
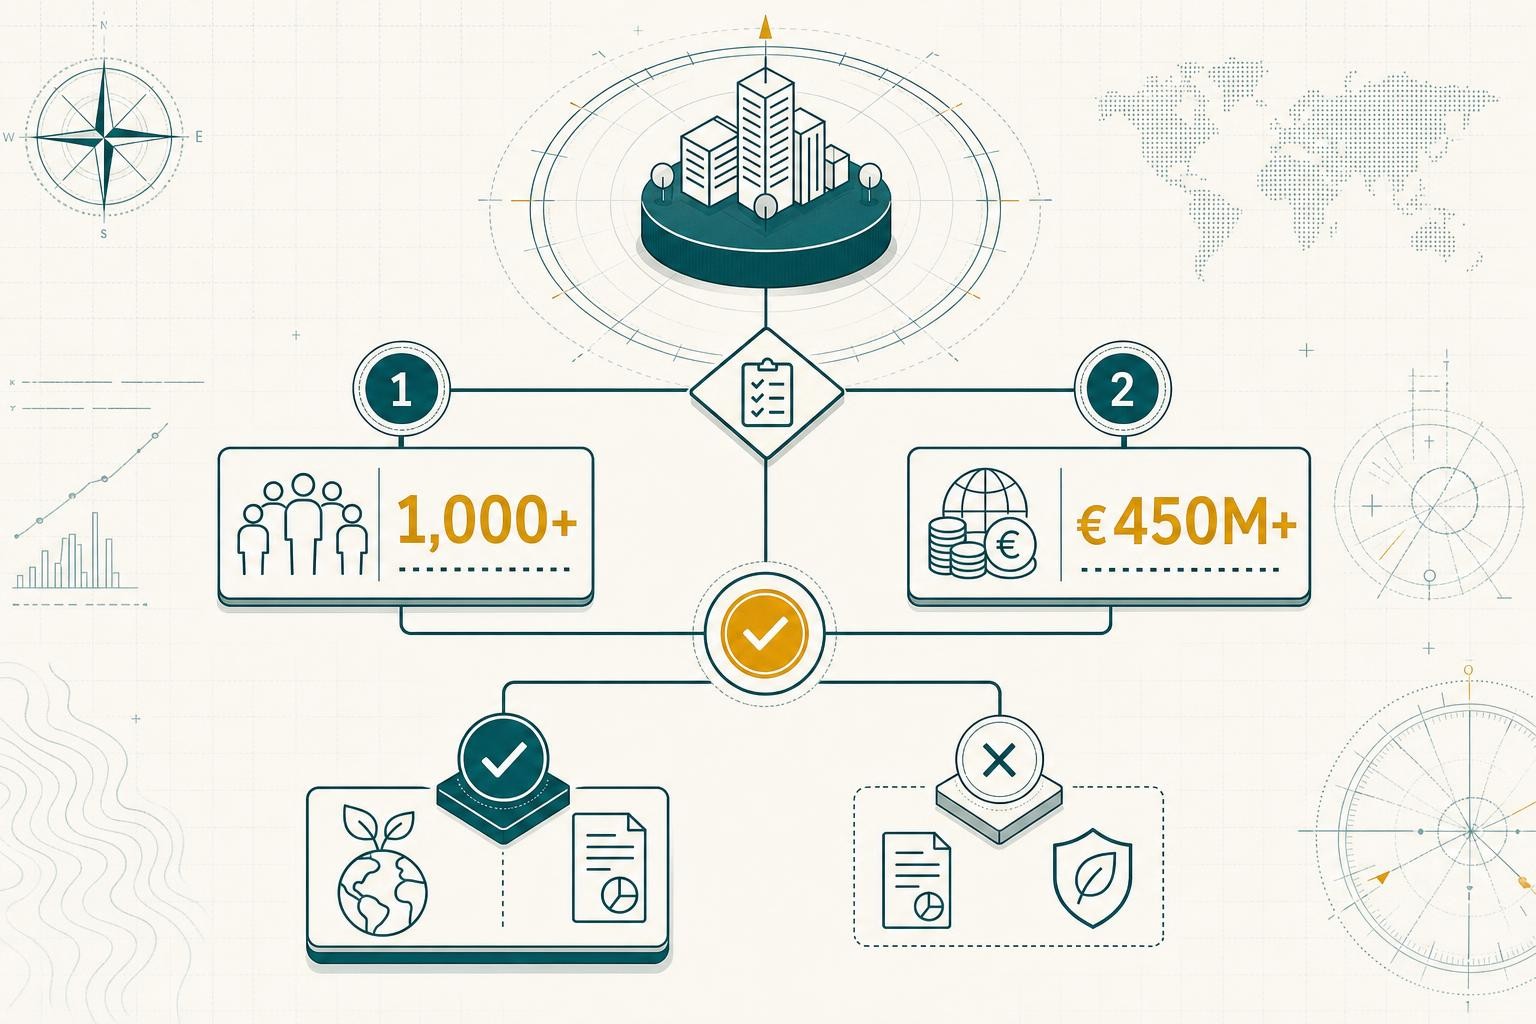
Am I in CSRD Scope for FY2027? The 1,000-Employee and €450M Turnover Test, Step by Step
After Omnibus I, CSRD applies only above both 1,000 employees and €450 million net turnover. Here is how to run the scope test properly: individual vs consolidated, how to count, the transition years, and the traps that catch groups out.
The EU Data Centre Rating Scheme and CSRD: Turning PUE and WUE Labels into ESRS E1 and E3 Evidence
The Commission has adopted a mandatory A-to-G rating scheme for larger data centres. It is not an ESRS metric, but the data behind it overlaps heavily with ESRS E1 and E3. Here is how to reuse it without conflating the two.
EU Taxonomy Disclosures Review: What the Platform's Two-Tier OpEx KPI Proposal Means for CSRD Reporters
The EU Platform on Sustainable Finance has recommended a two-tier OpEx KPI and the end of the weighted-average group KPI. These are recommendations, not law, but they show where Taxonomy reporting is heading. Here is what to do now and what to keep flexible.