How to Structure a CSRD Sustainability Statement: A Design Guide for ESRS 1 (2026)
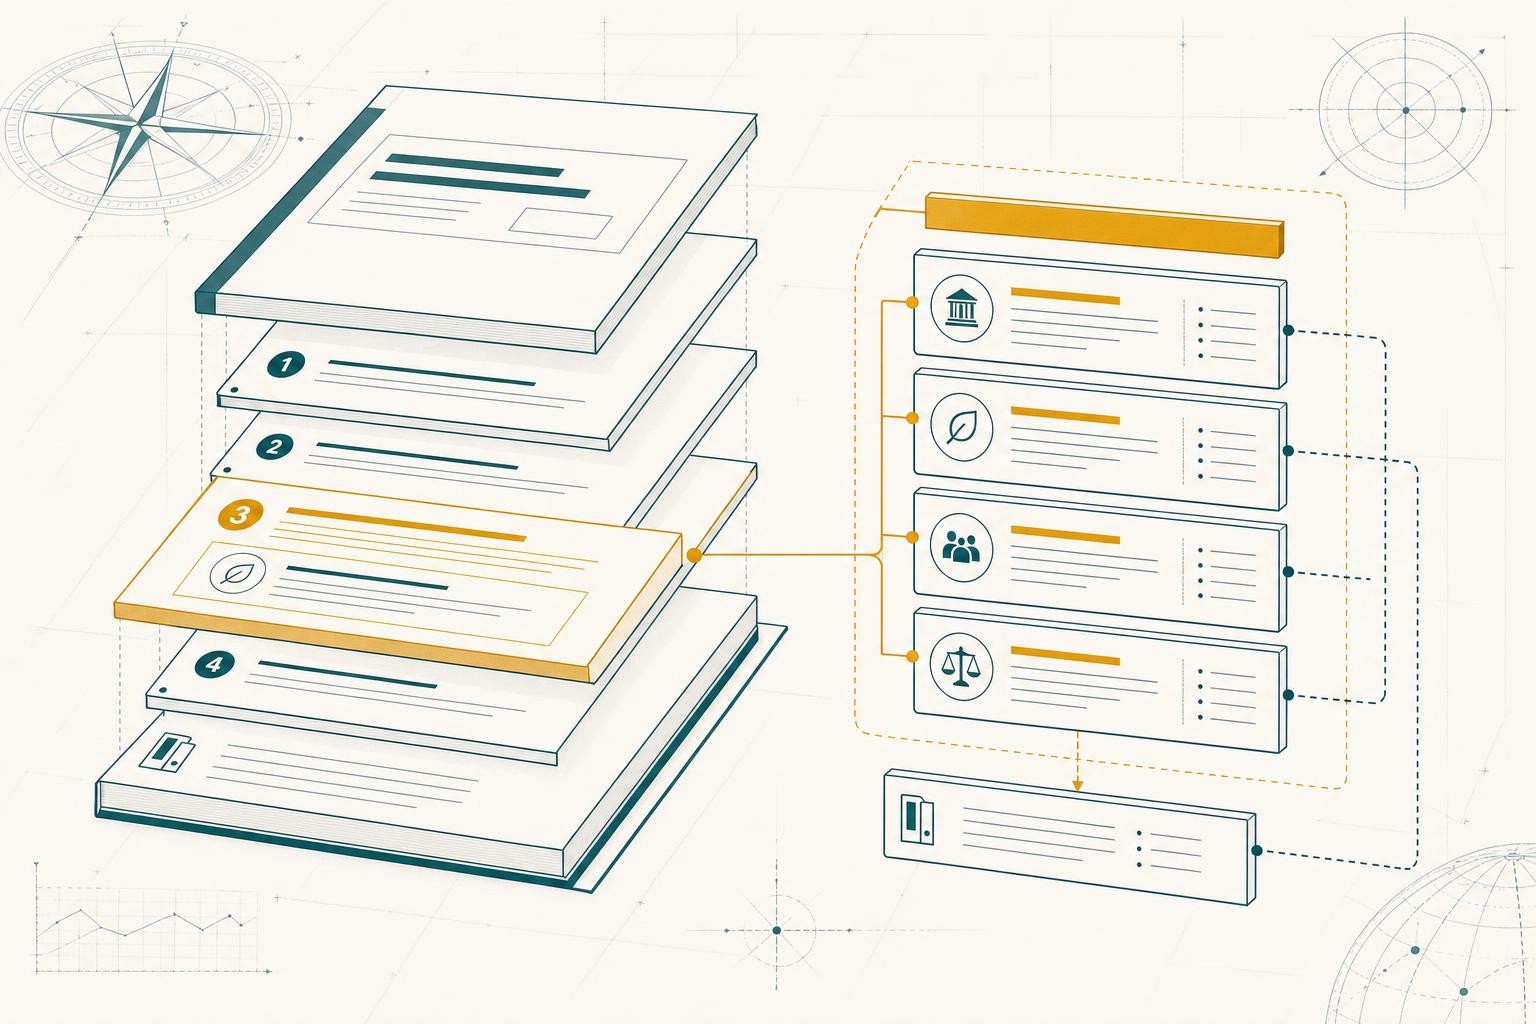
Wave 1 sustainability statements were, in many cases, genuinely hard to navigate. Hundreds of pages, no executive summary, EU Taxonomy tables buried mid-document, and a cross-reference table that was itself a navigation problem. That was partly a consequence of ESRS 1 (2023) saying almost nothing about what the document was allowed to look like. Preparers defaulted to "include everything, in standard order, in one block."
The revised ESRS 1, adopted by the European Commission on 3 July 2026, is mandatory from financial years beginning 1 January 2027, with voluntary early adoption permitted for FY2026. Paragraphs 103 to 111 of that revised standard introduce, for the first time, explicit structural options. This guide works through each of them - and tells you which ones to use.
1. Where the statement lives - and why it matters
The sustainability statement is not a separate ESG report. It is not a microsite. Under the CSRD, sustainability information must be disclosed in a dedicated, clearly identifiable section of the management report. That is a legal requirement, not a style preference.
The consequence is significant. The management report is the document the statutory auditor reads for consistency with the financial statements, and it is the document the assurance provider signs off on. All companies in scope for CSRD are required to obtain limited assurance from a third-party assurance provider from their first reporting year. Putting your sustainability statement somewhere else - a standalone PDF, a website - does not satisfy the requirement and puts the assurance opinion in an impossible position.
The management report also carries the iXBRL tagging obligation. Every material datapoint in the sustainability statement must be tagged using the ESRS XBRL taxonomy so the filing is machine-readable for the European Single Access Point. The mechanics of that tagging are covered in our ESRS digital tagging guide - the structural point here is simple: draft in a structure that survives tagging. Sections that move around late in the process create tagging errors. Lock the architecture early.
2. The mandated backbone: four parts, fixed order
ESRS 1 (2026) paragraph 105 requires the sustainability statement to be structured in four parts in the following order: general information, environmental information, social information, and governance information. That ordering is preserved from ESRS 1 (2023) and is not optional.
What sits inside each part, however, is almost entirely materiality-gated. If a topical standard is not material, you do not report under it - you explain why. The four-part spine is fixed; the content within it is not.
The practical implication: do not confuse the ordering requirement with a page-count requirement. A company for which only E1 (climate), S1 (own workforce), and G1 (business conduct) are material will have a short environmental section, a short social section, and a short governance section. That is correct. Padding non-material topics to look comprehensive is the wrong instinct.
The mandatory baseline that sits across all four parts is ESRS 2 - general disclosures on governance, strategy, materiality, and business model. Our ESRS 2 practitioner's guide covers those requirements in detail. For structural purposes, ESRS 2 content belongs in the general information part, and it is the one section every company must complete regardless of materiality outcomes.
3. The new structuring options: ESRS 1 (2026) paragraphs 103-111
ESRS 1 (2026) paragraphs 103-111 introduce new options for how an entity may structure its sustainability statement, including permitting the use of an executive summary, a specific appendix for EU Taxonomy-related information, appendices for more granular information, and tables of contents and mapping/cross-reference tables. Here is how to use each one.
Executive summary
Use it. The executive summary is where the board narrative belongs - a concise account of the company's most material impacts, risks, and opportunities, written for a reader who will not read the full statement. It is also the right place to signal what changed year-on-year and why. Keep it to three to five pages. Do not let it become a marketing document; the assurance provider reads it too.
EU Taxonomy appendix
Use it. The Taxonomy tables are the most template-driven, least readable content in any sustainability statement. They are also the content most likely to be read by a specialist audience (analysts, lenders, taxonomy-alignment checkers) rather than a general one. Isolating them in a dedicated appendix keeps the main body readable and makes the tables easier to find for the people who actually need them.
Granular appendices
Use them selectively. Long metric tables, entity-level breakdowns, methodology notes for GHG calculations, and lists of material sites are all good candidates for appendices. The test: if a disclosure requirement is satisfied by a summary figure in the main body, with the underlying detail available in an appendix, the main body is more readable and the appendix is more useful to specialists. Do not use appendices to hide information - the assurance provider will read them, and they remain part of the sustainability statement.
Table of contents and cross-reference/mapping tables
Use both. A table of contents is basic navigation hygiene for any document over 30 pages. A cross-reference table - mapping each ESRS disclosure requirement to the page or section where it is addressed - serves a second purpose: it shows the assurance provider, at a glance, what is covered and where. It also makes the materiality explanation visible: requirements that are not covered should appear in the table with a clear "not material" notation.
The cross-reference table is not just a reader aid — it is an assurance tool. Build it as a live document during drafting, not as a post-production exercise. If a disclosure requirement has no row in the table, it has no home in the statement.
4. Cross-referencing and incorporation by reference
Cross-referencing within the management report is permitted and encouraged. The conditions matter.
Disclosures incorporated by reference into the sustainability statement must constitute a separate element of information clearly identified as addressing the relevant disclosure requirement, be published before or at the same time as the management report, be in the same language as the sustainability statement, and be subject to at least the same level of assurance. They must also meet the same iXBRL tagging requirements.
The practical rule on scope: cross-referencing to another section of the same management report generally works. Cross-referencing to a separate document - a standalone remuneration report, a Pillar 3 disclosure, an EMAS report - is permitted from a defined list of sources, but each carries conditions. Cross-referencing to a website generally does not work: a webpage is not published at the same time, is not subject to assurance, and cannot be tagged.
When incorporating information by reference, the undertaking is required to consider the overall cohesiveness of the reported information and must ensure that the incorporation by reference does not impair the readability of the sustainability statement. That is a substantive test, not a formality. A sustainability statement that is mostly cross-references to other sections, with no coherent narrative of its own, fails the readability condition.
Where practice is still settling: The boundary between "clearly identified" cross-references that satisfy the conditions and references that merely gesture at information elsewhere is not yet tested by regulators or assurance providers at scale. Be conservative. If in doubt, include the information in the statement and cross-reference for additional context, rather than relying on the cross-reference as the primary disclosure.
5. Connectivity: making the statement agree with the financial statements
The assurance provider reads the sustainability statement and the financial statements together. That is not a formality - it is a substantive check.
The relationship and consistency between information disclosed in the sustainability statement and information provided in the financial statements is a key principle of the ESRS. Reconciliations are required where sustainability data intersects with financial data - for example, the carrying amount of assets subject to climate-related physical or transition risk, or the portion of revenue linked to EU Taxonomy-aligned activities.
Three practical rules for connectivity:
- Shared definitions. If the financial statements use a specific definition of "net revenue" or "capital expenditure," the sustainability statement must use the same one. Divergent definitions create apparent contradictions that the assurance provider will flag.
- Consistent consolidation scope. The sustainability statement should cover the same entities as the financial statements unless you have explicitly disclosed a different boundary and explained why. Orphan subsidiaries - entities in the financial consolidation but outside the sustainability boundary - are a common assurance finding.
- No orphan numbers. When the sustainability statement includes monetary amounts that exceed a threshold of materiality and are presented in the financial statements, the undertaking is required to include a reference to the relevant paragraph of its financial statements where the corresponding information can be found. Build those cross-references during drafting, not at the review stage.
6. Comparatives, phase-ins, and year-two coherence
In the first year of ESRS application, undertakings are not required to present comparative information for prior periods. That relief applies to both wave-one and wave-two preparers in their respective first years.
From year two onward, comparatives are required. The undertaking shall correct material prior period errors by restating the comparative amounts for the prior period(s) disclosed unless it is impracticable to do so, but this requirement does not extend to reporting periods before the first year of application of ESRS.
The structural implication: year one is the baseline. Treat it as such. Document every methodology choice - GHG calculation approach, consolidation boundary, materiality threshold - in enough detail that year two can either replicate or explicitly restate. A year-two statement that silently produces different numbers from year one is a credibility problem, even if the methodology improved. Signal changes; explain them; restate where required.
For phase-ins: ESRS 1 (2026) includes transitional provisions which permit entities to phase-in specific datapoints or topical reporting requirements over time, distinguishing between wave-one entities and other undertakings. Where a datapoint is phased in, say so explicitly in the statement - both in the relevant topical section and in the cross-reference table. Do not leave a blank with no explanation.
7. Entity-specific disclosures: when to add them, where they go
ESRS is a floor, not a ceiling. If a material impact, risk, or opportunity is not captured by any ESRS datapoint, you must still disclose it. That is the entity-specific disclosure obligation.
Two failure modes to avoid:
Adding noise. Entity-specific disclosures that restate what an ESRS datapoint already requires, or that describe immaterial topics in detail, inflate the statement without adding information. Every entity-specific disclosure should answer the question: "What would a reader miss if this were not here?"
Hiding a genuine impact. The more common failure. A company with a material impact - say, a significant land-use footprint, or a supply chain dependency on a conflict-affected region - that has no obvious ESRS home may be tempted to omit it. That is wrong. The fair presentation principle in ESRS 1 (2026) requires the statement to present all material information, not just information that fits a standard template.
Entity-specific disclosures sit within the relevant topical section of the four-part structure. They should be clearly labelled as entity-specific so readers and assurance providers can distinguish them from ESRS-mandated content.
8. A recommended skeleton
The table below shows a section-by-section outline of a well-structured sustainability statement, with indicative page weightings for a mid-size company with four to six material topics.
| Section | Content | Indicative pages |
|---|---|---|
| Executive summary | Key messages on material IROs; year-on-year highlights; board sign-off narrative | 3–5 |
| Part 1: General information (ESRS 2) | Governance, strategy, business model, double materiality process, basis of preparation | 15–25 |
| Part 2: Environmental (E1–E5) | Material topical standards only; non-material topics noted with explanation | 20–40 |
| Part 3: Social (S1–S4) | Material topical standards only; non-material topics noted with explanation | 15–30 |
| Part 4: Governance (G1) | Business conduct disclosures | 5–10 |
| Appendix A: EU Taxonomy | Taxonomy eligibility and alignment tables; KPI calculations | 10–20 |
| Appendix B: Methodology notes | GHG calculation methodology; data sources; estimation approaches; restatements | 5–10 |
| Appendix C: Cross-reference table | ESRS DR → page/section mapping; materiality status for each DR | 5–8 |
Total indicative length: 75-150 pages, depending on the number of material topics and the complexity of the EU Taxonomy disclosure. Wave 1 statements averaged significantly more than this. The reduction in mandatory datapoints - ESRS (2026) contains a 61% reduction in the number of mandatory datapoints compared to ESRS (2023) - should translate into shorter, more focused statements for FY2027 preparers.
9. Practical build advice
Draft in a structure that survives tagging. The iXBRL taxonomy maps to ESRS disclosure requirements, not to your document's heading hierarchy. If you restructure sections late in the process, tags break. Agree the final section structure before drafting begins, not after.
Control the boilerplate. The single biggest driver of statement length is boilerplate - standard descriptions of ESRS requirements, generic policy statements, and repeated definitions. Set a rule: if a paragraph could appear unchanged in any company's statement, cut it or compress it to one sentence.
Set a length target and enforce it. Pick a page budget before drafting. Assign page budgets to each section. Review against the budget at the halfway point, not at the end.
Run a navigation test. Before finalising, give the statement to someone who did not write it - ideally someone from the finance team rather than the sustainability team - and ask them to find five specific pieces of information. If they cannot find them in under two minutes each, the navigation structure needs work. The cross-reference table and table of contents exist to pass this test.
10. Action checklist
Agree with legal and finance that the sustainability statement will be a clearly identifiable, dedicated section of the management report — not a separate document. Confirm the iXBRL tagging workflow is in place before drafting begins.
Agree the section headings for all four parts before drafting. Include placeholders for non-material topics (with a one-line materiality explanation). Do not restructure after tagging has started.
For most preparers: use the executive summary, the EU Taxonomy appendix, a methodology appendix, and a cross-reference table. Build these into the structure from day one.
Start the ESRS DR → section/page mapping at the beginning of the drafting process. Use it to track coverage gaps and to communicate scope to the assurance provider.
Before drafting topical sections, confirm with the financial reporting team which definitions and consolidation boundaries apply. Document any differences and the rationale.
Every calculation approach, estimation method, and data source used in year one should be documented in enough detail to allow year-two restatement or explicit methodology change disclosure.
If you are voluntarily early-adopting ESRS (2026) for FY2026, you can apply the new structural options in paragraphs 103–111 immediately. You are not required to present comparative information for FY2025.
Ask someone outside the drafting team to locate five specific disclosures using only the table of contents and cross-reference table. Fix any failures before submission.
This article is guidance to help you understand ESRS 1 (2026) structural requirements. It is not legal or professional advice. Confirm specifics against the primary sources - in particular the adopted delegated act of 3 July 2026 - and seek qualified advice before relying on any conclusions for your own reporting.
Related reading
EU Pay Transparency Directive Meets ESRS S1: Why 2026 Is the Year Your Pay Data Gets Checked Twice
2026 is the reference year for both the EU Pay Transparency Directive and ESRS S1 pay gap metrics. If your two numbers differ and you can't explain why, that's a credibility problem in front of regulators, assurance providers, and works councils simultaneously.
"Undue Cost or Effort" Under ESRS 1 (2026): What Actually Changed for Value Chain Data
The revised ESRS 1 (adopted 3 July 2026) rewrites value chain data rules. Here's what changed, what the proportionality mechanism actually means, and how to document it for assurance.
UK SRS "Comply or Explain" vs CSRD: A Dual-Reporting Map for Groups Caught Between Both
The FCA has confirmed 'comply or explain' for UK sustainability disclosures while the EU's revised ESRS are now in the Official Journal. For groups with both UK and EU exposure, here is how the timelines and obligations line up.